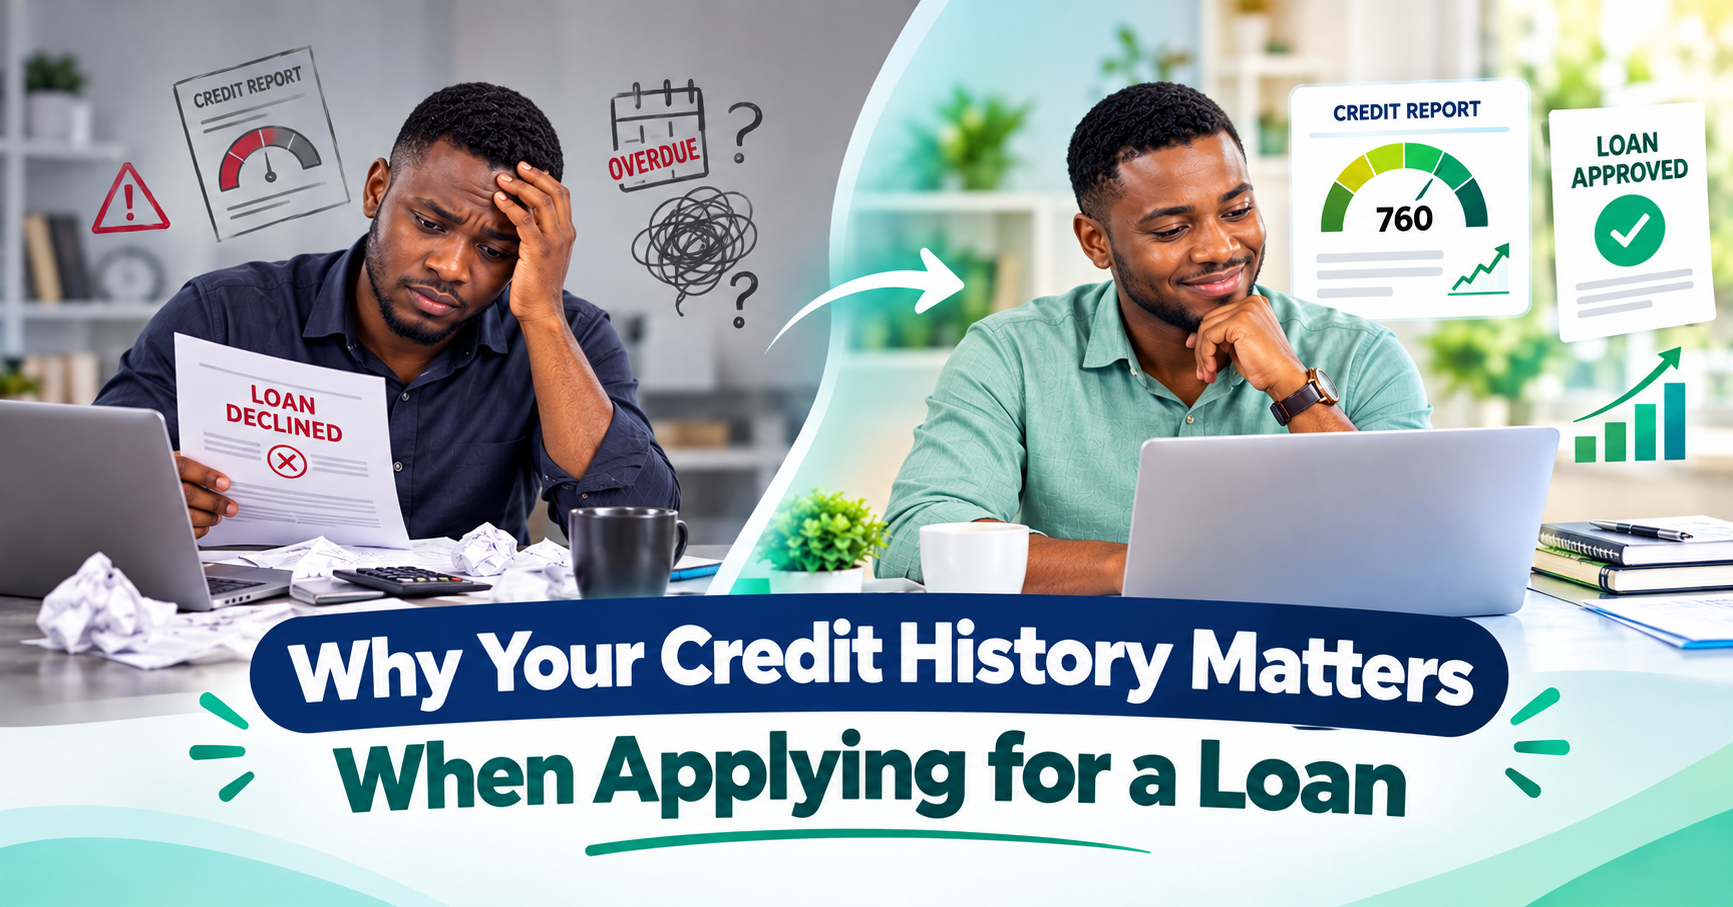
There is a message nobody wants to receive after applying for a highly needed loan. It usually looks like this:
“Application Declined: The facility request is declined due to the applicant’s poor credit history, with multiple non-performing/lost facilities reported across different lenders and total outstanding obligations of ₦812,399.00. Additional indebtedness/debt stacking was also observed, further increasing the applicant’s overall credit exposure. Based on the applicant’s credit history and existing obligations, the facility is not recommended for approval.”
Read it again. Now imagine it landing on your phone when you genuinely need the money.
Your first reaction is probably disappointment, then frustration. “But I need this money now. Why can’t I get the loan?”
That feeling is valid, but here’s the truth. From a lender’s side of the table, a loan application is never judged on the amount you asked for alone. The lender is also asking a harder question: what does this person’s existing financial life look like, and how have they handled borrowing in the past?
I write this post to break down what poor credit history, non-performing facilities and debt stacking actually mean, in plain language, and why they carry so much weight when you apply for new credit.
What Does a “Poor Credit History” Actually Mean?
Let’s forget the technical definition for a moment. Your credit history is simply a record of how you have borrowed and repaid over time. It carries information about the loans and credit facilities you have taken before, how your repayments went, what you still owe, and whether your facilities have been reported as performing or non-performing.
The part many people miss is that having borrowed before is not the problem. Someone who has taken a loan before has a better chance of having a good credit health than one who has never taken a loan. Lenders do not punish you for having a credit history. The question that really matters is how those loan obligations were managed.
Having a credit history is not the problem. A history of consistently unpaid or poorly serviced obligations can become the problem when you need to borrow again.
Think of it like a reputation among people who have lent you money before. One rough patch that you worked through tells a very different story from a pattern of borrowing and disappearing.
Read: Edubanc’s guide to assessing credit
What Happens when a Borrower Has Multiple Unpaid or Non-Performing Loans
Picture this. A customer has:
- Loan A – still carrying an outstanding balance
- Loan B – school fees loan, now overdue
- Loan C – reported as non-performing
Then they apply for another loan.
From where the lender sits, the question is simple and fair: can this person reasonably take on another obligation while the existing ones are still unpaid?
Past repayment behaviour is one of the strongest signals a lender has about future repayment behaviour. It does not mean every outstanding loan automatically leads to rejection. Life happens, and lenders know that. What matters is the full picture: your overall credit profile, how you have handled repayments, and how much exposure you already carry.
What Is Debt Stacking?
In simple terms, debt stacking is taking on multiple credit facilities from different lenders and piling up your total repayment obligations. One loan from here, another from there, a third from somewhere else, without fully servicing the earlier ones.
“A person takes a loan from one lender, then another, then another, without fully servicing the earlier obligations.”
The problem is not the number of loans by itself. Two well-managed loans are very different from five unmanaged ones. The real issue is the combined repayment burden, and whether you can realistically keep up with all of it.
Why Taking Another Loan May Not Solve an Existing Debt Problem
When the pressure is on and the temptation is powerful. You might think:
“I just need another loan to clear the other one.”
Here’s the truth. Sometimes refinancing or restructuring done responsibly with a clear plan, is a fair option. But repeatedly taking new credit without fixing the underlying repayment problem does something dangerous. It increases your overall exposure while the original problem quietly grows.
New credit should not simply become a way of postponing an existing repayment problem.
Before reaching for another loan, the wiser move is to face the full picture of what you owe. A new facility can be part of the solution, but it cannot be the whole strategy.
Your Credit History Is More Than Just a Number
Many people think of creditworthiness as a single score, one number that decides everything. The reality is broader than that.
Lenders look at a wider picture of your credit profile: the facilities you have taken before, how your repayments actually went, what you currently owe, and how all of it fits together. Your credit behaviour today is quietly writing the story that lenders will read tomorrow.
Why Non-Indebtedness and Responsible Borrowing Matter
Responsible borrowing is not about getting approved for the maximum amount available. It is about borrowing with your eyes open. It means:
- Know what you owe – keep track of every facility and balance
- Understand your repayment commitments – know exactly what leaves your account and when
- Avoid unnecessary borrowing – if it is not needed, don’t take it
- Pay existing facilities as agreed – on time, in full, as promised
- Don’t stack loans just because they are available – access is not the same as affordability
- Borrow for a clear purpose – every loan should have a job
- Keep new repayments manageable – alongside your existing commitments, not on top of them
A healthy borrowing profile is built over time, one kept promise at a time.
What Can You Do If You Have a Poor Credit History?
First, breathe. A poor credit history is a record of the past, not a sentence about your future. Here are practical steps, no judgment attached.
- Know what you owe – Make a list of every existing credit facility and its outstanding balance. You cannot fix what you have not faced.
- Prioritise repayment – Focus on bringing overdue obligations up to date where you can.
- Stop unnecessary debt stacking – Resist the urge to take additional loans just to cover recurring shortfalls. It deepens the hole.
- Keep records – Hold on to evidence of repayments and account closures. Paper trails protect you.
- Check your credit report – Review your credit information from a bureau licensed by Central Bank of Nigeria, such as FirstCentral or CRC, and make sure what is being reported about you is accurate. Errors happen, and you have the right to question them.
- Give your credit profile time to improve – Responsible repayment is a pattern, not a one-time action. Consistency is what rebuilds trust.
What Lenders Look At When You Apply for Credit
It helps to see the application the way a lender sees it. Different lenders have different policies and assessment criteria, so there is no single universal formula for approval. But these are the kinds of things that generally feed into a credit assessment:
Almost every lender is asking the same underlying question: based on this person’s history, can they handle this new commitment?
So… a declined application doesn’t have to define your financial future?
A declined application stings, but it can also be useful. Instead of rushing straight to another lender, treat it as information to ask important questions about your past credit facility. Ask:
- “What do I currently owe?”
- “Am I servicing my existing obligations?”
- “Are there facilities on my credit report that I have forgotten about?”
- “Am I taking on more debt than I can comfortably manage?”
Those are usually the better questions. Building a stronger credit profile starts with responsible borrowing and consistent repayment behaviour over time. A decline is a snapshot of where you are, not a verdict on where you are going.
Before You Apply for Your Next Loan
Use this checklist before your next application. Five minutes here can save you a rejection.
- Do I know my existing outstanding obligations?
- Am I currently behind on any loan repayments?
- Can I comfortably afford another repayment?
- Am I taking this loan for a clear purpose?
- Am I applying for another loan simply because I am struggling to repay an existing one?
- Have I reviewed my credit information for accuracy?
Thinking about applying for a loan?
Before you apply, take stock of your existing obligations and make sure the facility you are considering fits within your ability to repay.